How Much Should You Save for Retirement?
Rules of thumb, and why starting early matters most.
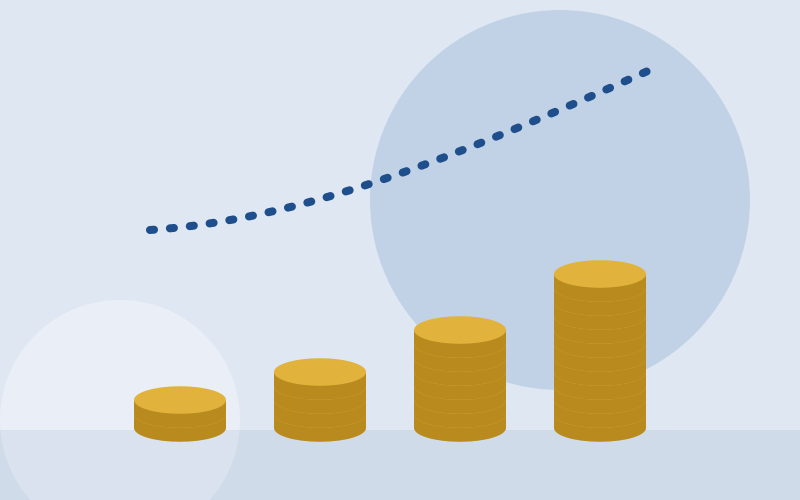
There’s no single right number, but common guidelines suggest saving around 10–15% of income over a working life, including any employer contributions. The earlier you start, the more compounding does the work.
Popular rules of thumb
Many planners suggest saving 10–15% of pre-tax income for retirement across a full career.
Another way to frame it is income replacement: aiming for savings that, with any public pension, replace a large share of your pre-retirement income.
Why time beats amount
Money saved in your twenties has decades longer to compound than money saved in your fifties.
Starting later usually means saving a larger share of income to reach the same goal.
Using employer and tax benefits
If an employer matches contributions, capturing the full match is often one of the best returns available.
Tax-advantaged retirement accounts vary by country, but they can significantly increase what you keep over time.
Raise your savings rate by one percentage point each time you get a raise. You’ll barely feel it, and it adds up.
Frequently asked questions
What is the “4% rule”?
A rough guideline suggesting withdrawing about 4% of savings in the first year of retirement, then adjusting for inflation. It’s a starting point, not a guarantee.
Is it too late to start at 50?
No. It may require saving more and working a bit longer, but every year of saving helps.
This guide explains a general concept; it isn’t a recommendation to buy, sell or borrow. For decisions about your own money, consider speaking with a licensed financial professional.